By Azabache Producciones on
Invoice booklets: numbering authorization must be checked before printing
Numbering authorization and the format’s intended use determine when an invoice booklet can be printed and used in Colombia.
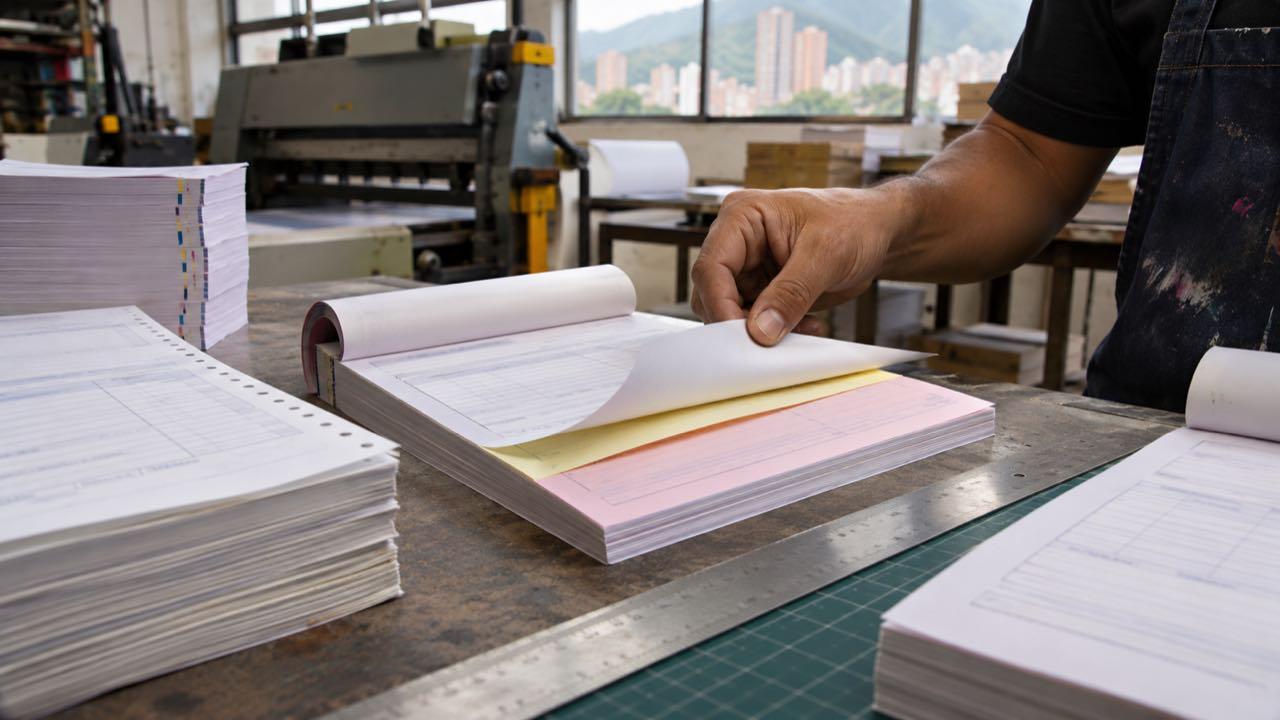
An invoice booklet does not begin with paper or the number of copies. Numbering authorization has to be settled before it goes to print, because the printed format is usable only under the conditions that apply to the issuer. Numbering authorization determines whether an invoice booklet can be sent to print.
DIAN Resolution 000227 of 2025 compiles the current tax regulation on sales invoices and the invoicing system, according to Colombia’s tax and customs authority, DIAN. It does not make the booklet a freely available alternative to electronic invoicing. Paper invoices follow different rules according to the issuer’s tax and technological situation.
The graphic order needs to be kept separate from the tax procedure, even though the two connect. In corporate stationery production in Medellín, format, quantity and copies can be tailored to administrative use, while an invoice additionally requires the applicable supporting documents. An administrative form and a sales invoice do not automatically receive the same treatment.
What should be checked before printing invoice booklets?
Before a paper invoice booklet is printed, the customer supplies the printer registered in the RUT with a copy of the official numbering-authorization document. The compiled regulation also prevents invoices from being produced with authorizations not issued by DIAN. A copy of the authorization accompanies an order for paper invoice booklets.
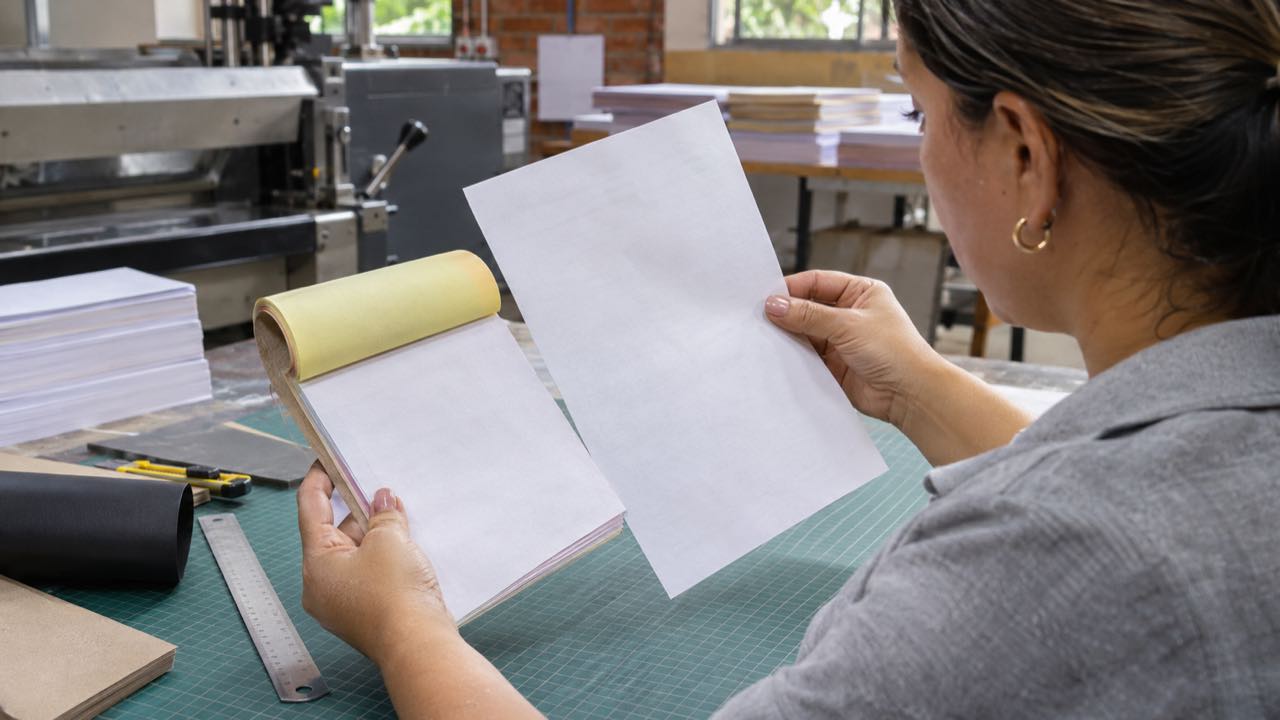
Print worker compares an authorization with numbered booklet sheets. Illustrative image generated with artificial intelligence.
The printer must consult the authorization and register the production, including the number of invoices printed, under DIAN’s compiled resolution. For that reason, the numbering, authorized range and requested quantity need to match between the document and the production order. The number of invoices printed is part of the printer’s production record.
When can invoice booklets be used?
Paper invoice booklets are recognized by the regulation, but for a party required to invoice electronically, their use applies when a technological problem prevents electronic invoicing. The regulation also covers the stated case for SIMPLE taxpayers who were not previously required to invoice electronically. A booklet does not replace electronic invoicing at the issuer’s own discretion when it is required.
DIAN’s invoicing-numbering service includes paper sales-invoice booklets and states a maximum authorization validity of 24 months. That validity alone does not determine how each format may be used; use depends on the issuer’s condition and on the situation that gives rise to the paper invoice. Numbering authorization has a maximum validity of 24 months.
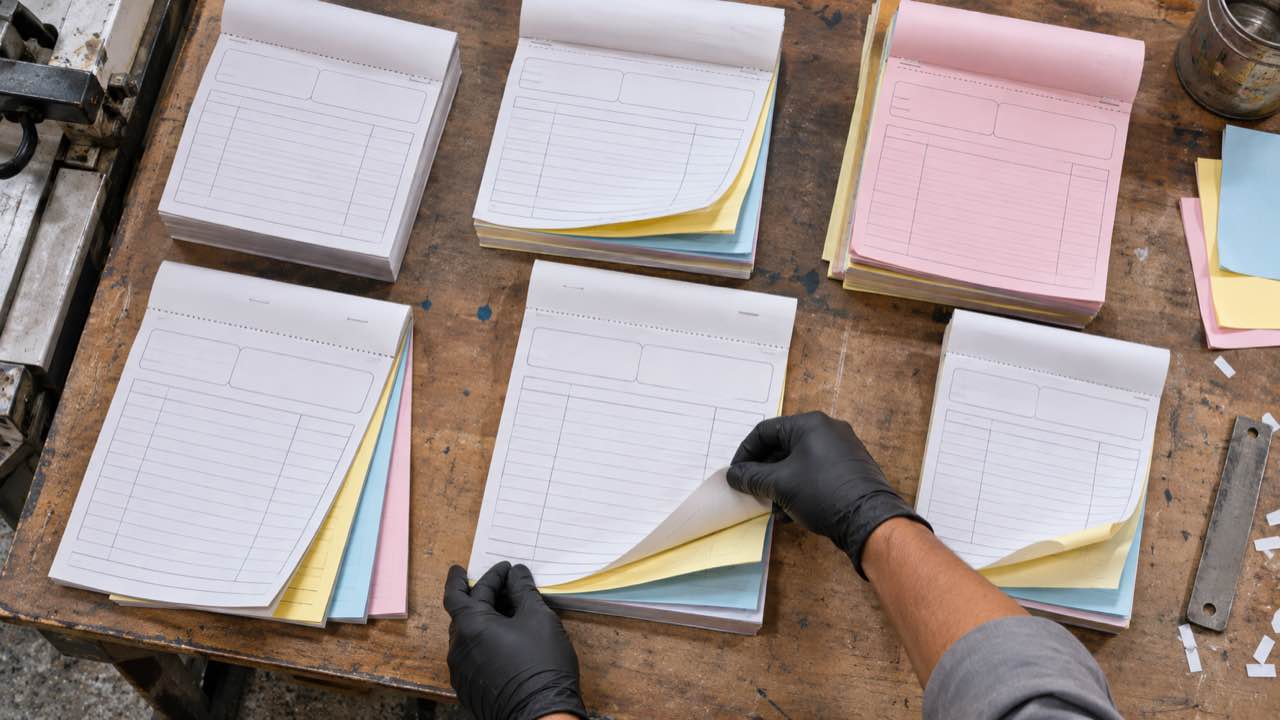
Receipt and invoice booklets separated on a production table. Illustrative image generated with artificial intelligence.
Do receipt booklets follow the same rules as invoices?
Not necessarily. A booklet for receipts, deliveries or internal control may need data, copies and numbering suited to its operation, but it should not automatically be presented as a sales invoice. The tax effect of a format depends on its use and on the status of its issuer.
Cost has no universal figure: it changes with quantity, size, copies, material, printing and finish. Nor is there a standard lead time for every order; run size and production conditions should appear in writing in the quote. A comparable quote describes the format and the full production conditions.